Skip to free estimate

Independent diminished value appraisals

Your car was repaired.
Its value wasn’t.

An accident stays on your car’s history. We document the value it lost and prepare the appraisal and demand letter for your insurance claim.

Check my claim for free

Takes about 2 minutes. No payment required.
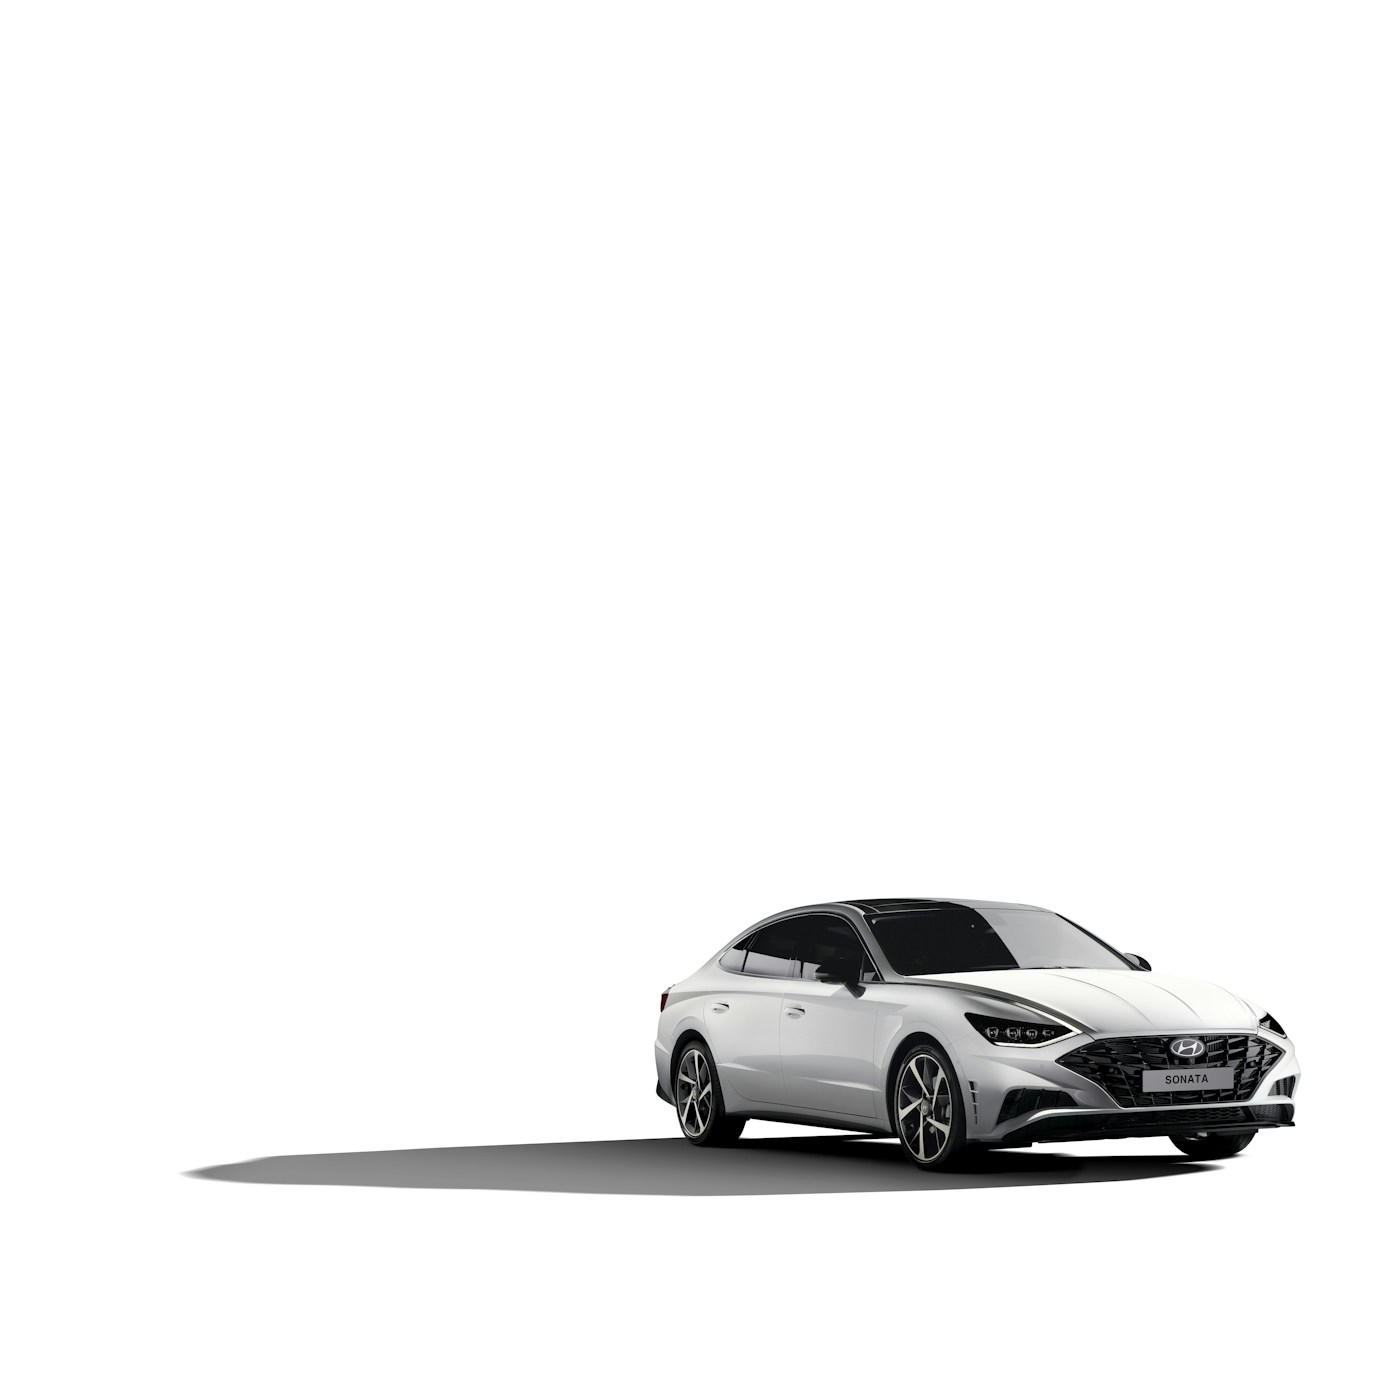
Before the accident

White Hyundai Sonata, illustrative vehicle
$30,000

Market value with a clean history

After repairs

Same illustrative car, fully repaired
$26,500

Market value with accident history

Diminished value$3,500
Illustrative example. Actual diminished value varies by vehicle and accident.

How it works.

Check your eligibility.

Answer a few questions about your accident and vehicle. Start with a free estimate before buying a report.

Get your appraisal.

Choose your report and upload your repair documents. We prepare and personally review your appraisal.

Submit your claim.

Send your appraisal and tailored demand letter to the insurer, with response templates to help you follow up.

*Report delivery within 48 hours of receiving your completed intake and all required documentation.

Free Estimate

Start with your accident.

Answer a few questions to see whether your claim qualifies.

Step 1 of 8
Did another driver cause this accident?
DV claims are filed against the at-fault driver's insurance — not your own.
Yes — the other driver was at fault
Most common scenario — you very likely qualify
Not sure yet — fault is still being determined
No problem — we can still estimate your potential recovery
Partially — we both share some fault
You may still qualify if the other driver shares any responsibility
Other driver was at fault but had no insurance
Without a third-party insurer there's no DV claim to pursue
No — I caused the accident
DV claims require an at-fault third party — you likely won't qualify
Step 2 of 8
When did the accident happen?
DV claims have a filing deadline that varies by state — often two to three years.
Within the last 12 months
1 – 2 years ago
2 – 3 years ago
More than 3 years ago
Step 3 of 8
Have you already settled or signed a release for this claim?
Signing a full release for the damage claim usually waives the diminished value too.
No — my claim is still open
I only settled the repair cost — no full release
Yes — I signed a full release / final settlement
Step 4 of 8
What state did the accident happen in?
We serve 48 states. We do not serve Nebraska or Oregon.
Step 5 of 8
How much were the repairs?
Claims under $1,500 rarely produce meaningful DV recovery.
$3,500 – $7,000
$1,500 – $3,500
Over $7,000
Under $1,500
My car was declared a total loss
Step 6 of 8
Tell us about your vehicle.
Newer, lower-mileage vehicles have higher DV recovery potential.
What year is your vehicle?
Approximate mileage?
Title status before the accident?
Step 7 of 8
Was there any structural or frame damage?
Structural damage significantly increases your potential recovery.
Yes — frame or structural damage confirmed
No — cosmetic damage only
Not sure — I'd need to check the repair invoice
Step 8 of 8
Did your vehicle have any prior accident history before this claim?
Previous accidents reduce a vehicle's pre-loss value and can lower your DV recovery.
No — clean history before this accident
Yes — minor prior damage (no structural)
Yes — significant prior damage
No credit card · No commitment

A claim backed
by evidence.

You receive a personally reviewed appraisal, a letter to send to the insurer, and guidance for following up.

Independent diminished value appraisal

A documented assessment of your vehicle’s lost market value, using its condition, repair history, and market comparisons.

A demand letter for your insurer

Your claim laid out in writing, ready for you to review and send with the appraisal.

Support for the next response

Counter-response templates, insurer strategy notes, and a Department of Insurance complaint letter.

One report. One flat fee.

Choose based on the damage listed on your repair invoice.

Standard appraisal

For cosmetic repairs—panels, paint, dents, or glass—with no structural damage.

$199.50$399

Includes your diminished value appraisal, market comparisons, insurer-specific demand letter, and response templates.

Structural appraisal

For frame or unibody damage, structural repairs, or airbag deployment.

$249.50$499

Everything in Standard, plus a Structural Impact Statement, frame-damage history analysis, and reinforced demand language.

Founding rate: 50% off through September 30. In exchange, we ask for an honest review after your claim is resolved.

A clear guarantee

If the diminished value we document is less than your report fee, we refund the fee in full. See our terms.

Prepared within 48 hours

From receipt of your completed intake and required documents. Both reports include insurer strategy notes and a DOI complaint letter.
Bryan Dastmalchi, founder of Value Reclaimed

Personally reviewed.
Personally accountable.

I’m Bryan Dastmalchi, founder of Value Reclaimed. I spent fourteen years in finance assessing value and defending the numbers. I personally review and sign every report we deliver.

If you have a question before ordering, email me directly at hello@valuereclaimed.com.

Still have questions?

What if my claim was already settled?
+
It depends on what you signed. If you signed a full release that specifically included diminished value, you may have waived your right. If the settlement only covered repairs and medical bills, your DV claim may still be open. When in doubt, get the free estimate — it costs nothing to find out.
What states do you serve?
+
We serve clients in 48 states. We do not serve Nebraska (no established legal basis for third-party DV claims) or Oregon (Oregon law requires DV reports to be signed by a state-licensed appraiser, a credential we do not hold).
Can I file a DV claim on a leased vehicle?
+
Usually, yes. Leased vehicles add some legal complexity because the leasing company holds the title, but lessees typically have standing to pursue diminished value against the at-fault driver's insurance — particularly in strong-DV states. Outcomes depend on your lease terms and state law. If we review your paperwork after purchase and determine there's a fundamental standing issue that would prevent recovery, your report fee is refunded in full under our guarantee.
What's your refund policy?
+
Simple: if the diminished value we document is less than the cost of the report, you get a full refund. If we can't find you more than you paid us, you don't pay. We also pre-screen every claim before accepting payment — if we don't think your claim has merit, we'll tell you that for free before you spend anything.
How do I know Value Reclaimed is legitimate?
+
Payment runs through Stripe, so we never see your card details. You can view a full sample report before paying, so you know exactly what you're buying. Every report is prepared and signed by a named appraiser — Bryan Dastmalchi, founder — not an anonymous company. And the guarantee is simple: if the diminished value we document is less than the cost of your report, you don't pay. We also decline cases that don't qualify, free, at the estimate stage.
How long does it take to get my report?
+
Standard turnaround is 48 hours from the time you submit your completed intake form with all required documentation. In most cases it's faster. Your full appraisal, demand letter, DOI complaint letter, and insurer strategy notes are delivered by email — all human-reviewed before they leave our desk.
What do I need to upload?
+
The main thing you need is your repair invoice — the itemized estimate or final bill from the body shop showing the total repair cost. If you have the other driver's insurance claim number, that's helpful but not required. We'll guide you through everything on the intake form after payment. Most people complete it in under 10 minutes.
What if the insurer ignores my demand letter or lowballs me?
+
Every report includes counter-response templates for exactly this situation. If the insurer stonewalls or comes back with a lowball offer, you have pre-drafted language ready to go — including escalation to the state DOI. In our experience, a filed DOI complaint changes the dynamic quickly. Insurers know that a regulatory complaint creates a paper trail they'd rather avoid.
Do I need a lawyer?
+
No. The demand letter, DOI complaint, and counter-response templates in your report are designed to be sent directly by you, without any legal representation. Most DV claims settle through the insurer's claims process without ever involving an attorney or court. If your claim is unusually large or the insurer is actively hostile, an attorney may be worth consulting — but the vast majority of clients handle this entirely on their own.
Who generates my report?
+
Every report is built using a USPAP-informed methodology and personally reviewed by a finance professional before it leaves the desk. Reports are not auto-generated and are not outsourced. If it wouldn't pass a professional valuation review, it doesn't ship.

Find out if your car has a claim.

Check your eligibility before paying for an appraisal.

Check my claim for free
Get Free Estimate — No Credit Card →
Sample Report
What's included — Standard Report
⚡ Founding Rate · 50% Off
You're paying the founding rate — 50% off every report through September 30.
🛡️ Full refund guarantee — if we can't document more than the report cost, you pay nothing.
Confirm & Pay →
Personally reviewed & signed by Bryan Dastmalchi, founder

By clicking you agree to our Terms of Service. Secure checkout via Stripe — we never see your card details.

What Is Diminished Value?
01
The accident creates a permanent record
The repair gets paid and the car looks fine — but the accident is now permanently on your Carfax. Every future buyer and dealer will see it. That record doesn't disappear after repairs.
02
Your car is worth thousands less — permanently
Buyers discount accident-history vehicles significantly. The same car with a clean Carfax sells for measurably more. That gap between what your car would have been worth vs. what it's worth now is your diminished value.
03
In 48 states, the at-fault insurer owes you that loss
The law in most states requires the at-fault driver's insurer to compensate you for diminished value — not just repair costs. Insurers won't volunteer this. Most people never know to ask.
04
But you need certified documentation to collect
A verbal claim won't hold. You need a USPAP-informed appraisal backed by real market comp data, a demand letter written for your specific insurer, and a strategy for when they push back. That's what we build.